

USD: A refocus on the here and now may be the dollar’s best outcome
Markets have been rather confused about how to process the midterms outcome. In the immediate aftermath, equities and Treasuries, particularly at the long end, rallied. Much of it looked like a relief rally, with investors shrugging off election uncertainty, perhaps helped along by President Trump’s acceptance of the result.
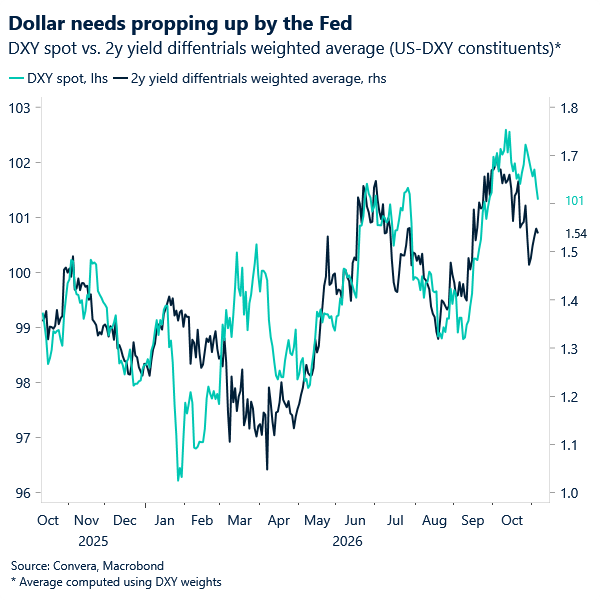
But remember, the narrative dominating headlines into the midterms was that of a more tightly regulated AI future under Democratic control. That has weighed on the case for a hawkish Fed and, by extension, the dollar.
Overnight, tech stocks came under renewed selling pressure, with the Kospi down 5%, while more traditional sectors, particularly consumer names, found demand. This pointed to a rotation out of tech rather than a broader market selloff. The dollar is trading on the back foot into the London open.
Meanwhile, US labour market data has continued to surprise to the upside this week. Yesterday’s ADP report showed the private sector added 86k jobs in October, adding to a strong JOLTS release earlier this week. The next key test comes with Friday’s nonfarm payrolls report.
Markets may still be struggling to settle on a clear narrative, but the path ahead looks more straightforward. The bullish case for the dollar continues to hinge on Fed hawkishness (mainly via conflict-induced inflation pressures) and, increasingly, the US AI-driven resilient growth story. For now, we see little reason for either to begin weakening.
Investors are desperate to refocus on the here and now, which means incoming economic data and developments in oil markets. On the latter, Brent crude is trading at its lowest level in more than a month after President Trump signalled little intention to resume strikes in the Middle East, easing concerns that he had been waiting for the midterms before re-escalating tensions. This adds to a growing run of reports suggesting both the US and Iran are increasingly open to diplomacy. Still, given the conflict’s history, it is probably too early to place much weight on this.
DXY should hold 101 support comfortably into the weekend, barring a dovish surprise in Friday’s payrolls report.
EUR: Inflation lands, euro gains elusive
Eurozone inflation rose to 4.0% in October, up from 3.8% in the previous month and in line with expectations. Meanwhile, the core component, which strips out food and energy, held steady at 2.5%.
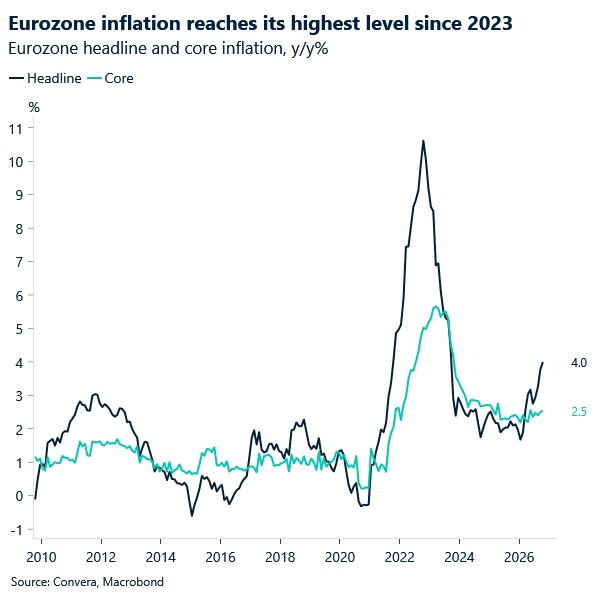
The report suggests inflation pressures continue to be driven by higher energy prices, with little sign of meaningful second-round effects.
The euro was largely indifferent to the outcome. That comes as little surprise, as the euro has largely stopped responding to ECB developments since the conflict in the Middle East began. France’s fiscal turmoil has only weakened the link further.
It was telling that market-implied expectations for the ECB’s next move in December were little changed after the release. Markets continue to price around an 88% chance of a hike, not quite confident enough to go the whole way. This clearly signals continued hesitation, as France-induced higher yields chip away at the need for further ECB-driven monetary tightening.
France-driven bearishness appears to have eased. We see that in EUR/CHF, which has found buying interest near 0.915. Remember, this pair remains the clearest expression of the fiscal woes facing the eurozone’s second-largest economy.
EUR/USD moved higher in the wake of the midterm election, although sellers continue to emerge around 1.1250. That resistance is likely to strengthen further if tomorrow’s NFP report delivers a strong upside surprise.
GBP: BoE set to hike, but will it blink?
Sterling enters today’s Bank of England (BoE) meeting from a position of strength. GBP/USD has tested 1.35, helped largely by post-election dollar weakness in the US, while GBP/EUR remains near 1.20, a level rarely seen over the past decade. Recent inflation, labour market and GDP data have all surprised to the upside, reinforcing expectations that Bank Rate will be raised by 25bp to 4.00% today – it’s first hike in three years. Yet sterling might be vulnerable.
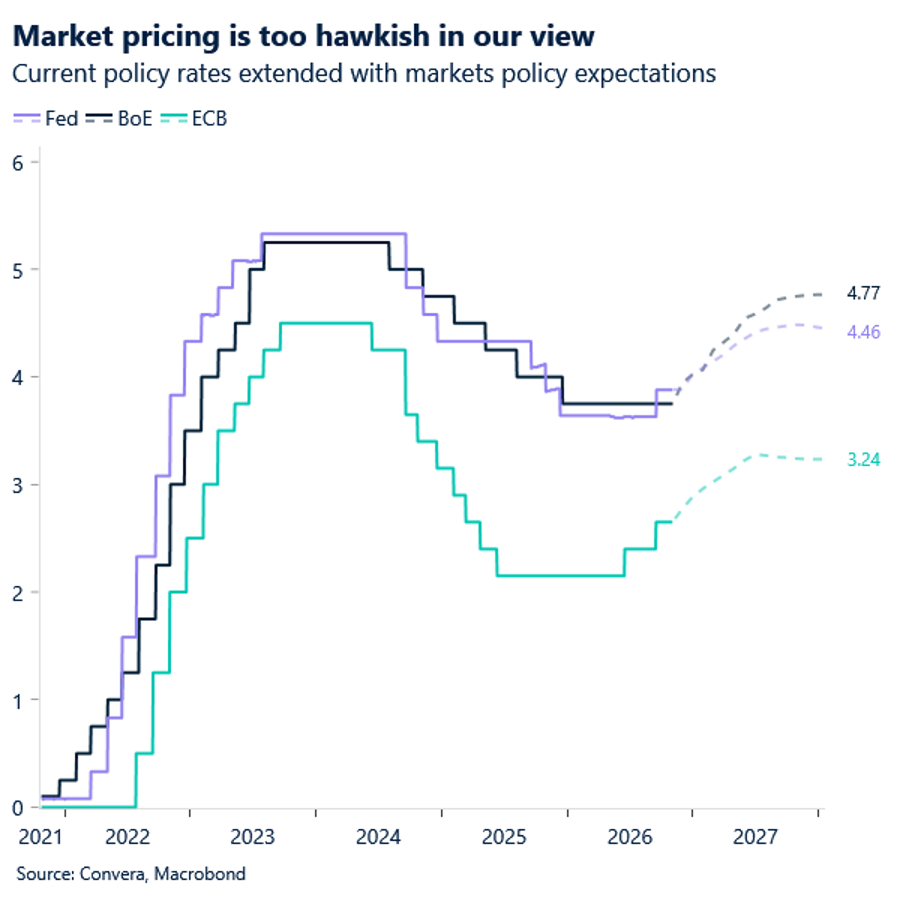
The hike itself is not the story . With markets assigning around a 95% probability to such an outcome, attention instead turns to the vote split, updated forecasts and Governor Bailey’s guidance. Markets currently price almost 100bp of additional tightening through late 2027, a path that looks increasingly ambitious in our view. If the BoE pushes back against those expectations, the resulting dovish repricing in rates could prove more important for sterling than the hike itself.
The BoE faces a delicate balancing act. On one hand, higher energy prices are likely to push inflation above 4% in coming months, while stronger growth and a firmer labour market make further tightening easier to justify. On the other, there remains little evidence of meaningful second-round inflation effects. Wage growth has slowed materially, vacancies continue to trend lower and underlying inflation pressures remain far less acute than during the 2022 inflation shock.
That leaves scope for a dovish hike. The MPC may raise rates today as a risk-management exercise while simultaneously signalling scepticism towards the aggressive path currently priced by markets. If so, gilt yields would fall and drag sterling lower via the rates channel.
For now, the pound remains supported by its carry appeal and improving domestic data. But with positioning already heavily skewed towards further tightening, the hurdle for a genuinely sterling-positive BoE surprise looks high.
Market snapshot
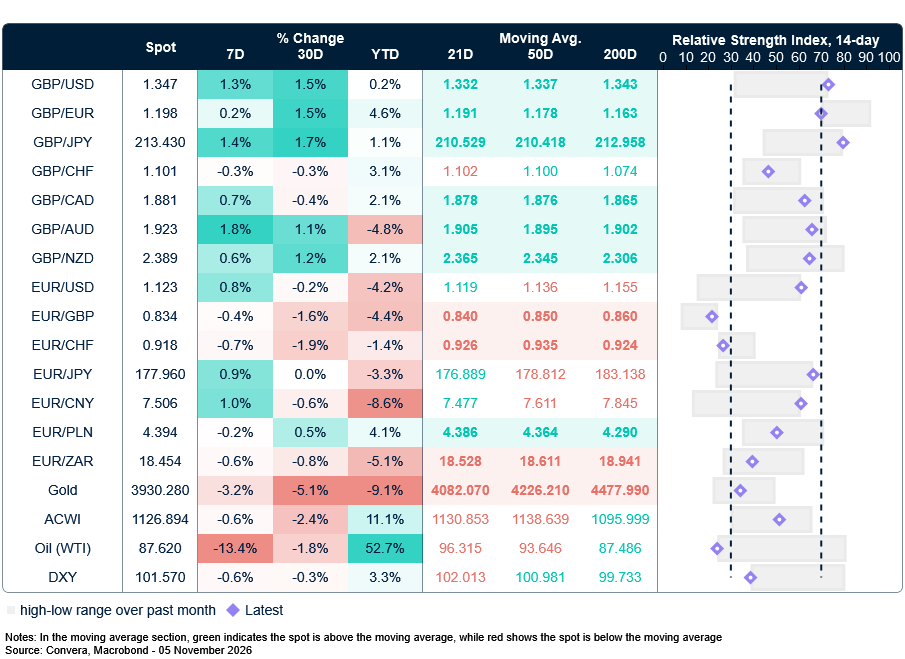
Table: Currency trends, trading ranges & technical indicators
Key global risk events
Calendar: November 02-06
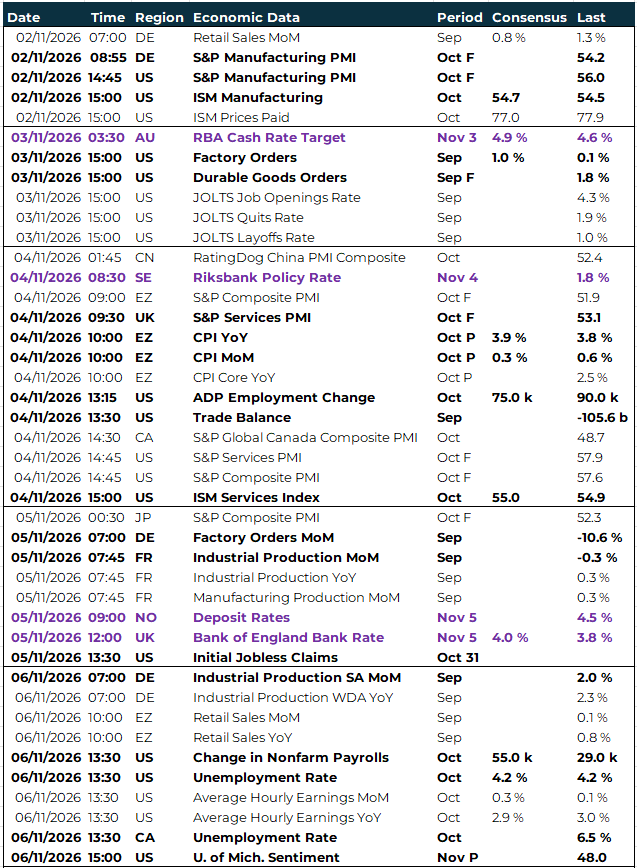
All times are in GMT
Have a question? [email protected]
*The FX rates published are provided by Convera’s Market Insights team for research purposes only. The rates have a unique source and may not align to any live exchange rates quoted on other sites. They are not an indication of actual buy/sell rates, or a financial offer.