

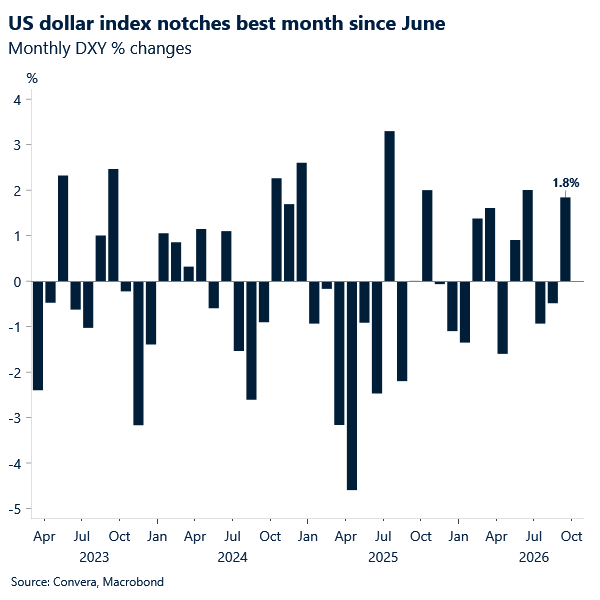
USD: Dollar on track for strongest monthly run since June
The last few days have seen a familiar cycle of “deal on, deal off” headlines, after several months of relative silence amid stalled efforts to resolve the Middle East conflict.
Iran appears committed to its proposal to reopen the Strait of Hormuz, an offer Trump rejected over the weekend. That said, talks look set to resume this week.
Oil and broader risk sentiment remain the most sensitive to swings in geopolitics, while G10 FX has become more anchored as central bank policy outlooks reassert themselves as the key driver.
The dollar index (DXY) closed relatively flat yesterday, while oil surged ~4% at one stage. Those gains faded later in the session amid reports that Saudi Arabia resumed exports through a key pipeline after Houthi disruptions earlier in the month.
But for the dollar, data remains the clearest catalyst for further hawkish repricing ahead of October’s decision and, in turn, continued support for the currency. Today’s JOLTS layoffs data is followed by ADP figures and PCE inflation tomorrow, with Friday’s jobs report rounding off a busy week.
However, the more consequential release remains September CPI on 14 October, the only CPI print before the decision.
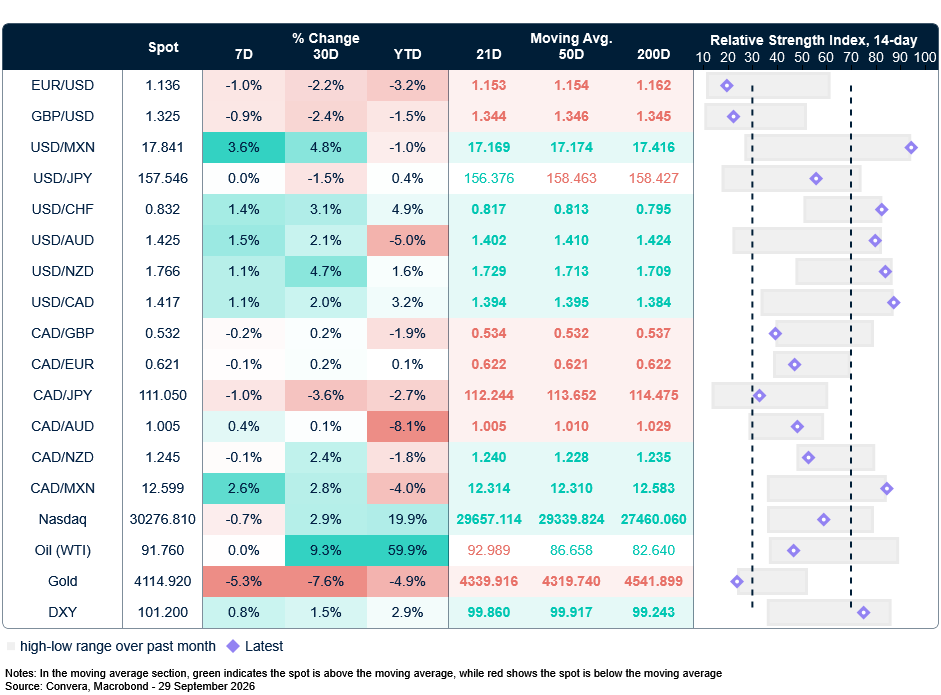
The dollar index appears to be consolidating just above the 101 mark, having risen nearly 2% this month. Summer highs at 101.640, followed by 101.800, are firmly in focus, albeit conditional on incoming data.
EUR: Near three-month low
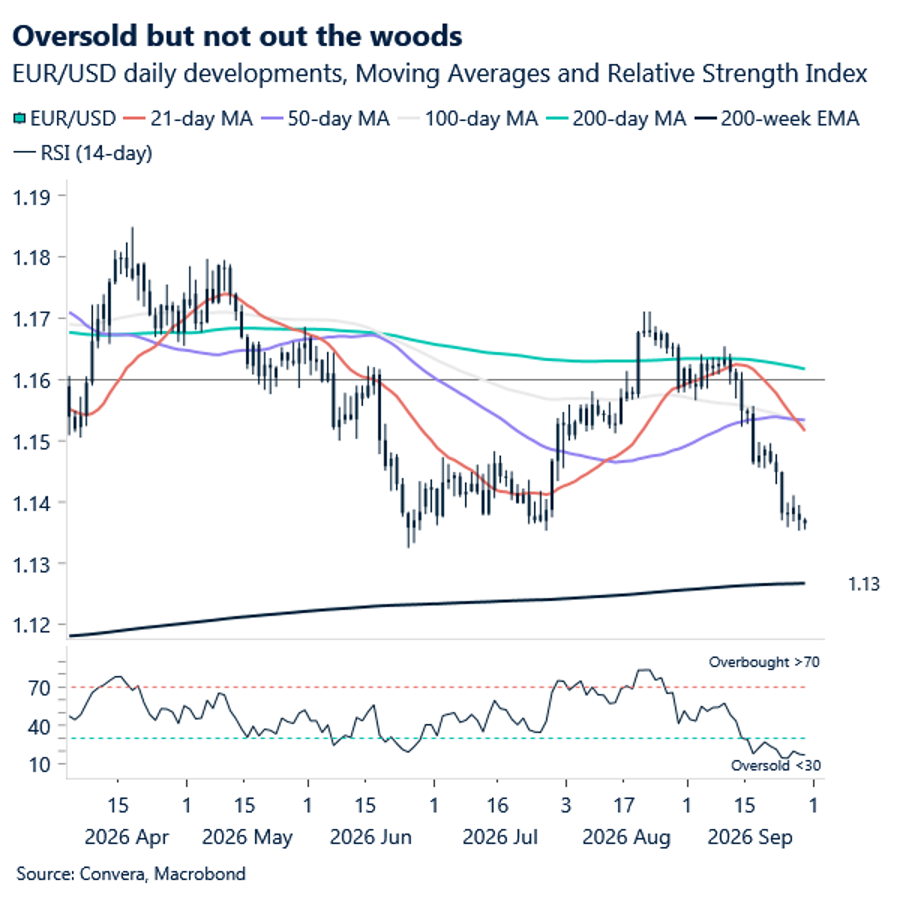
The euro remains under pressure, with EUR/USD trading near its weakest levels since late July, as markets continue to focus on relative rates rather than domestic eurozone developments. The daily relative strength index is in oversold territory, but spot could still trend towards 1.13 before consolidating.
While upcoming country-level inflation releases and confidence indicators will be watched closely, they are unlikely to meaningfully shift the narrative.
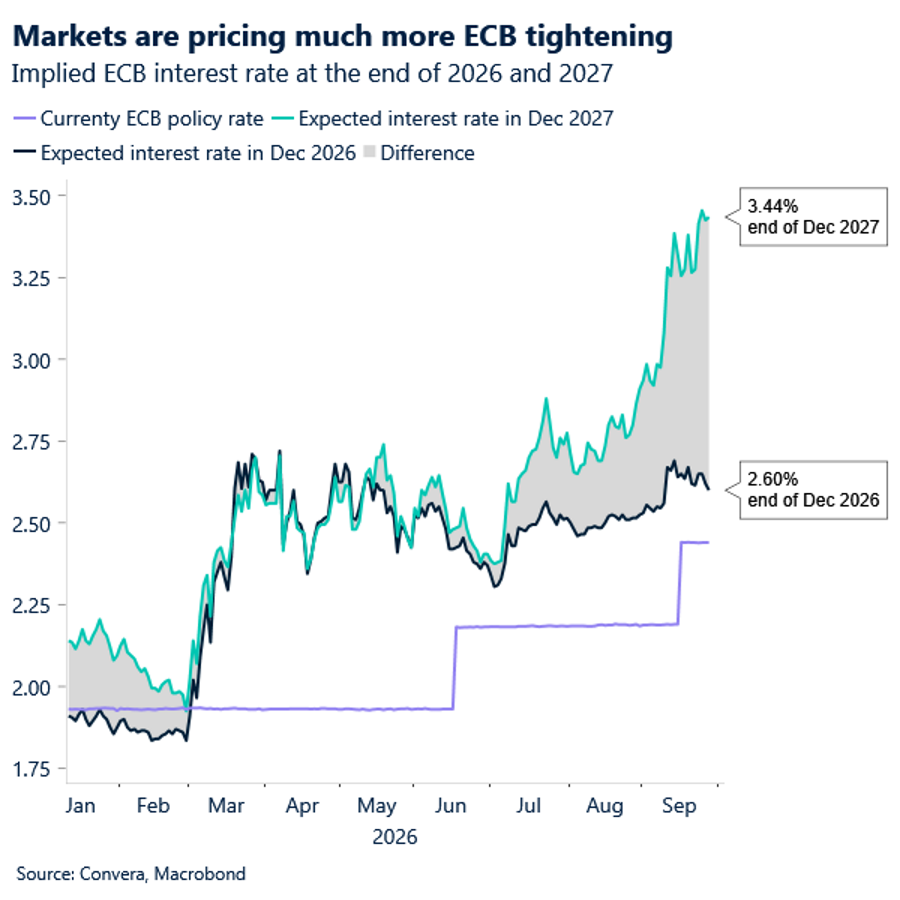
The key issue for the euro is that the ECB is becoming increasingly conscious of the growth costs of higher rates. President Lagarde reiterated on Monday that wage pressures have yet to show a significant response to higher energy prices, while also acknowledging that rising long-term market rates are already acting as a brake on activity. That suggests the ECB remains committed to a measured and data-dependent approach, despite the renewed energy shock.
As we have highlighted recently, this makes the roughly 100bp of additional tightening priced by late 2027 look vulnerable if growth momentum slows. The contrast between sentiment and activity remains notable. Consumer confidence continues to lag, reflecting pressure on households from higher energy costs and broader uncertainty. Yet business activity and investment trends remain more resilient, helped by structural spending themes and stronger corporate demand.
For EUR/USD, however, the immediate focus remains elsewhere. Energy prices, Fed expectations and broader risk sentiment continue to dominate price action, leaving the euro vulnerable to further downside unless those headwinds begin to ease.
GBP: Pragmatism pays
It was somewhat ironic to see long-end gilt yields surge yesterday as oil prices jumped, while sterling rallied across the board.
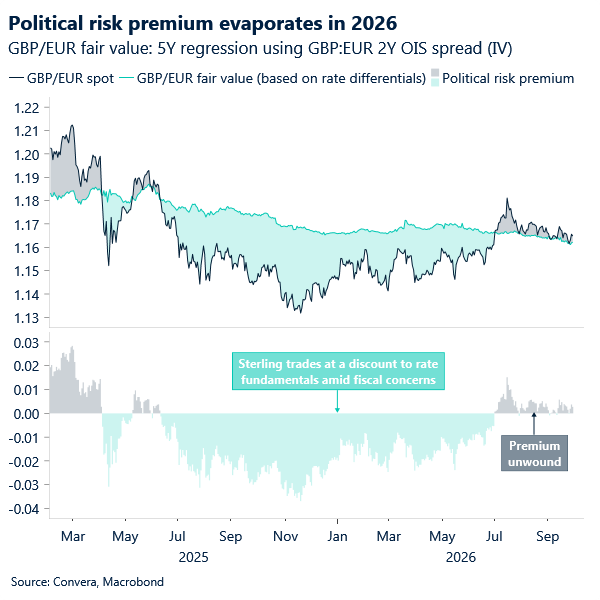
It comes down to the origin of the shock. Back in 2025, long-end gilt yields rose on UK-specific concerns around fiscal discipline. Today, those risks are increasingly being shared across markets as an external consequence of the conflict in the Middle East. Against that backdrop, sterling no longer automatically sells off when long-end yields rise.
Meanwhile, sterling’s rally can be largely attributed to Chancellor Healey’s speech at the Labour Party conference. Once again, the Chancellor reiterated the government’s commitment to sticking to its fiscal rules. At one point, he described the current level of debt as “an affront to our values”.
He hailed a “new age of industrialisation”, announcing a number of related policy initiatives. At the same time, however, he stressed that the money available to New Labour in the 1990s is “simply not there now”.
As we hinted in yesterday’s report, the best outcome for UK assets would be a Budget defined by pragmatism and caution rather than ambition, reflecting the harsher reality created by the conflict in the Middle East. Expectations for major spending commitments or significant tax rises seem limited. That may be precisely what markets want to hear, given the challenging geopolitical backdrop and the pressure it is placing on government borrowing costs.
Meanwhile, a narrowing of fiscal headroom is increasingly seen as an unavoidable consequence of largely external forces.
GBP/EUR jumped 0.4% to a one-week high yesterday, taking off from support near 1.1620. More headlines from the Labour Party conference are due today, with Andy Burnham’s speech likely to be the key event.
We could see some further upside in sterling crosses given how positively markets seem to be digesting the messaging from the new administration. That said, we would not expect a meaningful extension higher for now. In GBP/EUR, the 1.1670-1.690 area should cap gains over the coming days.
Market snapshot
Table: Currency trends, trading ranges & technical indicators
Key global risk events
Calendar: September 28 – October 02
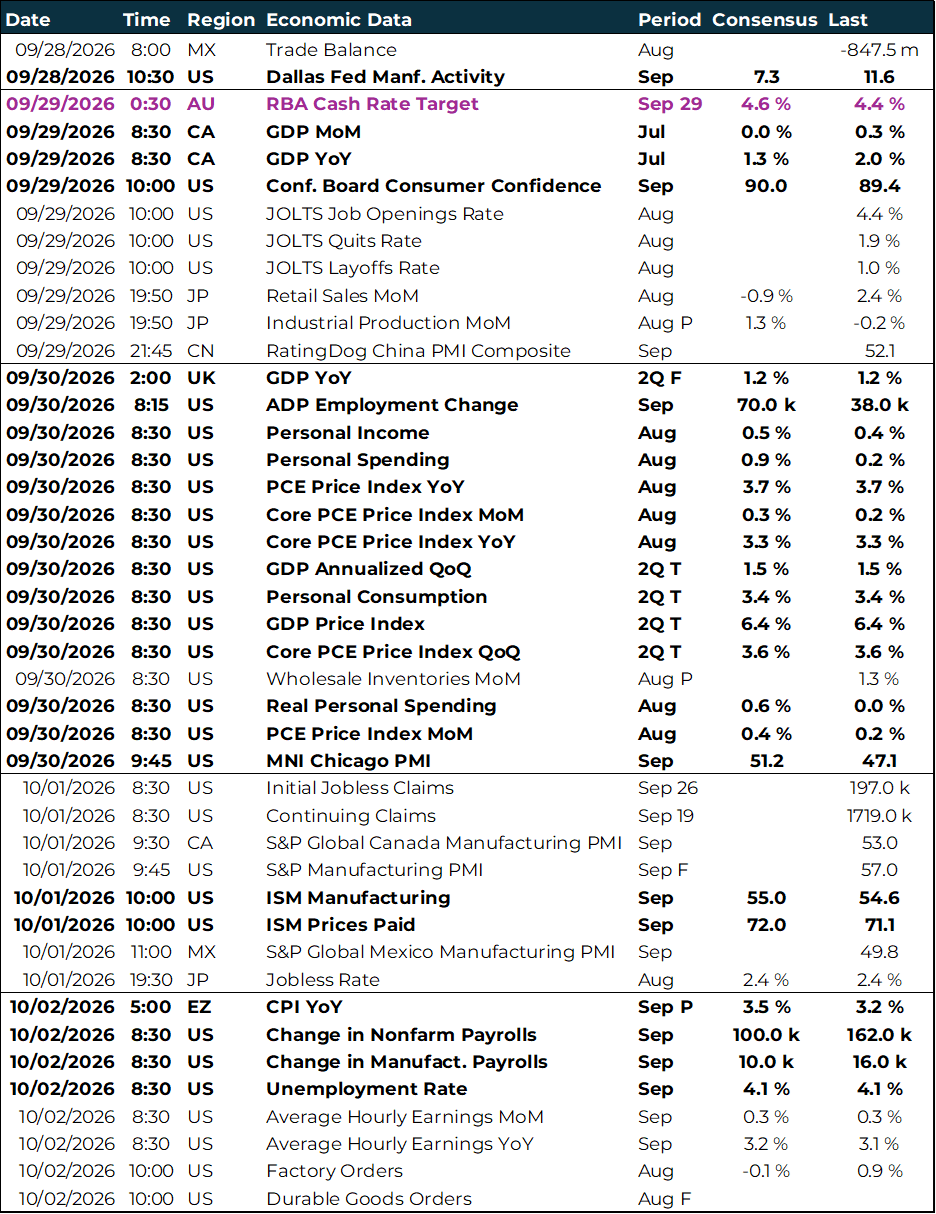
All times are in EST
Have a question? [email protected]
*The FX rates published are provided by Convera’s Market Insights team for research purposes only. The rates have a unique source and may not align to any live exchange rates quoted on other sites. They are not an indication of actual buy/sell rates, or a financial offer.