
Key Takeaways
- AI concerns are weighing on the dollar by pulling Treasury yields lower and challenging the US growth and investment premium.
- The loonie has strengthened through 1.40 as resilient retail spending and rising Bank of Canada hike expectations narrow its rate disadvantage.
- With an October hike largely priced, further CAD gains now depend on hawkish BoC guidance and broader confirmation of Canadian economic resilience.
- The peso’s carry support continues to break down as its yield advantage slips below 300 basis points and unresolved trade tensions add to local risks.
- Relative-rate momentum is now pushing CAD and MXN in opposite directions, with Canadian spreads narrowing as Mexico’s carry cushion erodes.
When AI doubts become US dollar risks
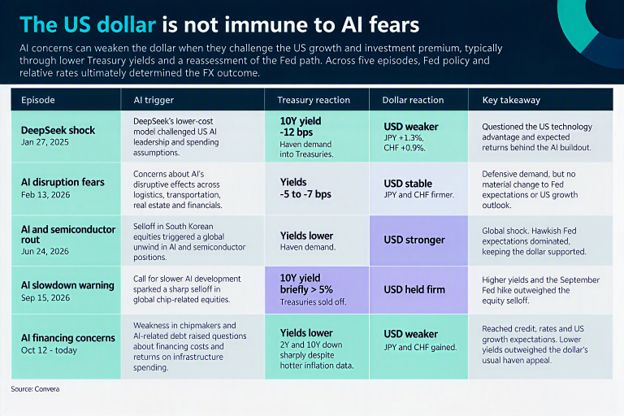
Last two weeks exposed a growing vulnerability in the dollar. Concerns about the AI investment cycle pulled Treasury yields lower, and the dollar followed, even as stronger US inflation data pointed in the opposite direction. The move went beyond weaker technology stocks. Markets began questioning the growth, financing and investment premium attached to the US AI buildout. Once those doubts reached Treasury yields and Fed expectations, the dollar’s rate advantage weakened, while the yen and Swiss franc offered cleaner protection from a shock centred on US assets.
AI concerns have affected FX before, but the outcome depends on what part of the US outlook they challenge. Across five identifiable episodes since January 2025, only DeepSeek and last week produced a clear combination of lower Treasury yields and a weaker dollar. Both shocks questioned a specific US advantage. DeepSeek challenged American AI leadership and the scale of spending required to defend it, while last week shifted attention toward financing costs and the returns that spending will ultimately generate. In the other episodes, the dollar was largely unaffected or strengthened because Fed policy, inflation and broader risk aversion carried more weight.
That does not establish a new structural regime, but it broadens the channels through which AI concerns can reach FX. Treasury demand, Fed expectations, AI-related credit, US investment and foreign exposure to American technology assets can now move together. Relative rates remain the key transmission mechanism. If doubts about AI reduce expectations for US investment or growth, investors can seek protection in Treasuries while pricing a softer Fed path, pulling yields and the dollar lower alongside equities. The dollar’s usual haven support can then be outweighed by the loss of its rate and growth advantage.
Through the end of 2026, a hawkish Fed and elevated US real yields should keep the dollar broadly supported. AI-driven selloffs are more likely to produce temporary corrections unless stress spreads through credit markets or companies begin cutting capital expenditure. Last week’s Treasury rally did not resolve the fiscal problem either, with heavy government borrowing and rising interest costs still reflected in yields and term premium. A sustained dollar decline would require the AI correction to weaken expected US investment and growth, bring forward Fed easing and narrow relative real-rate differentials. Without that sequence, the dollar can recover even if technology shares remain volatile.
The risk becomes more important in 2027 as investors move from rewarding AI spending to assessing its returns. Data-centre utilization, revenue growth, energy costs, refinancing conditions and hyperscaler capex guidance will show whether the investment cycle can support its current scale. Strong monetization would preserve the US growth premium and remain supportive for the dollar. Weak returns and tighter financing conditions would slow investment and challenge one of the foundations of US exceptionalism. The dollar therefore remains supported while confidence in the US AI premium holds, but its exposure increases if that confidence begins to fade.
Retail strength extends Loonie’s rate-driven rally
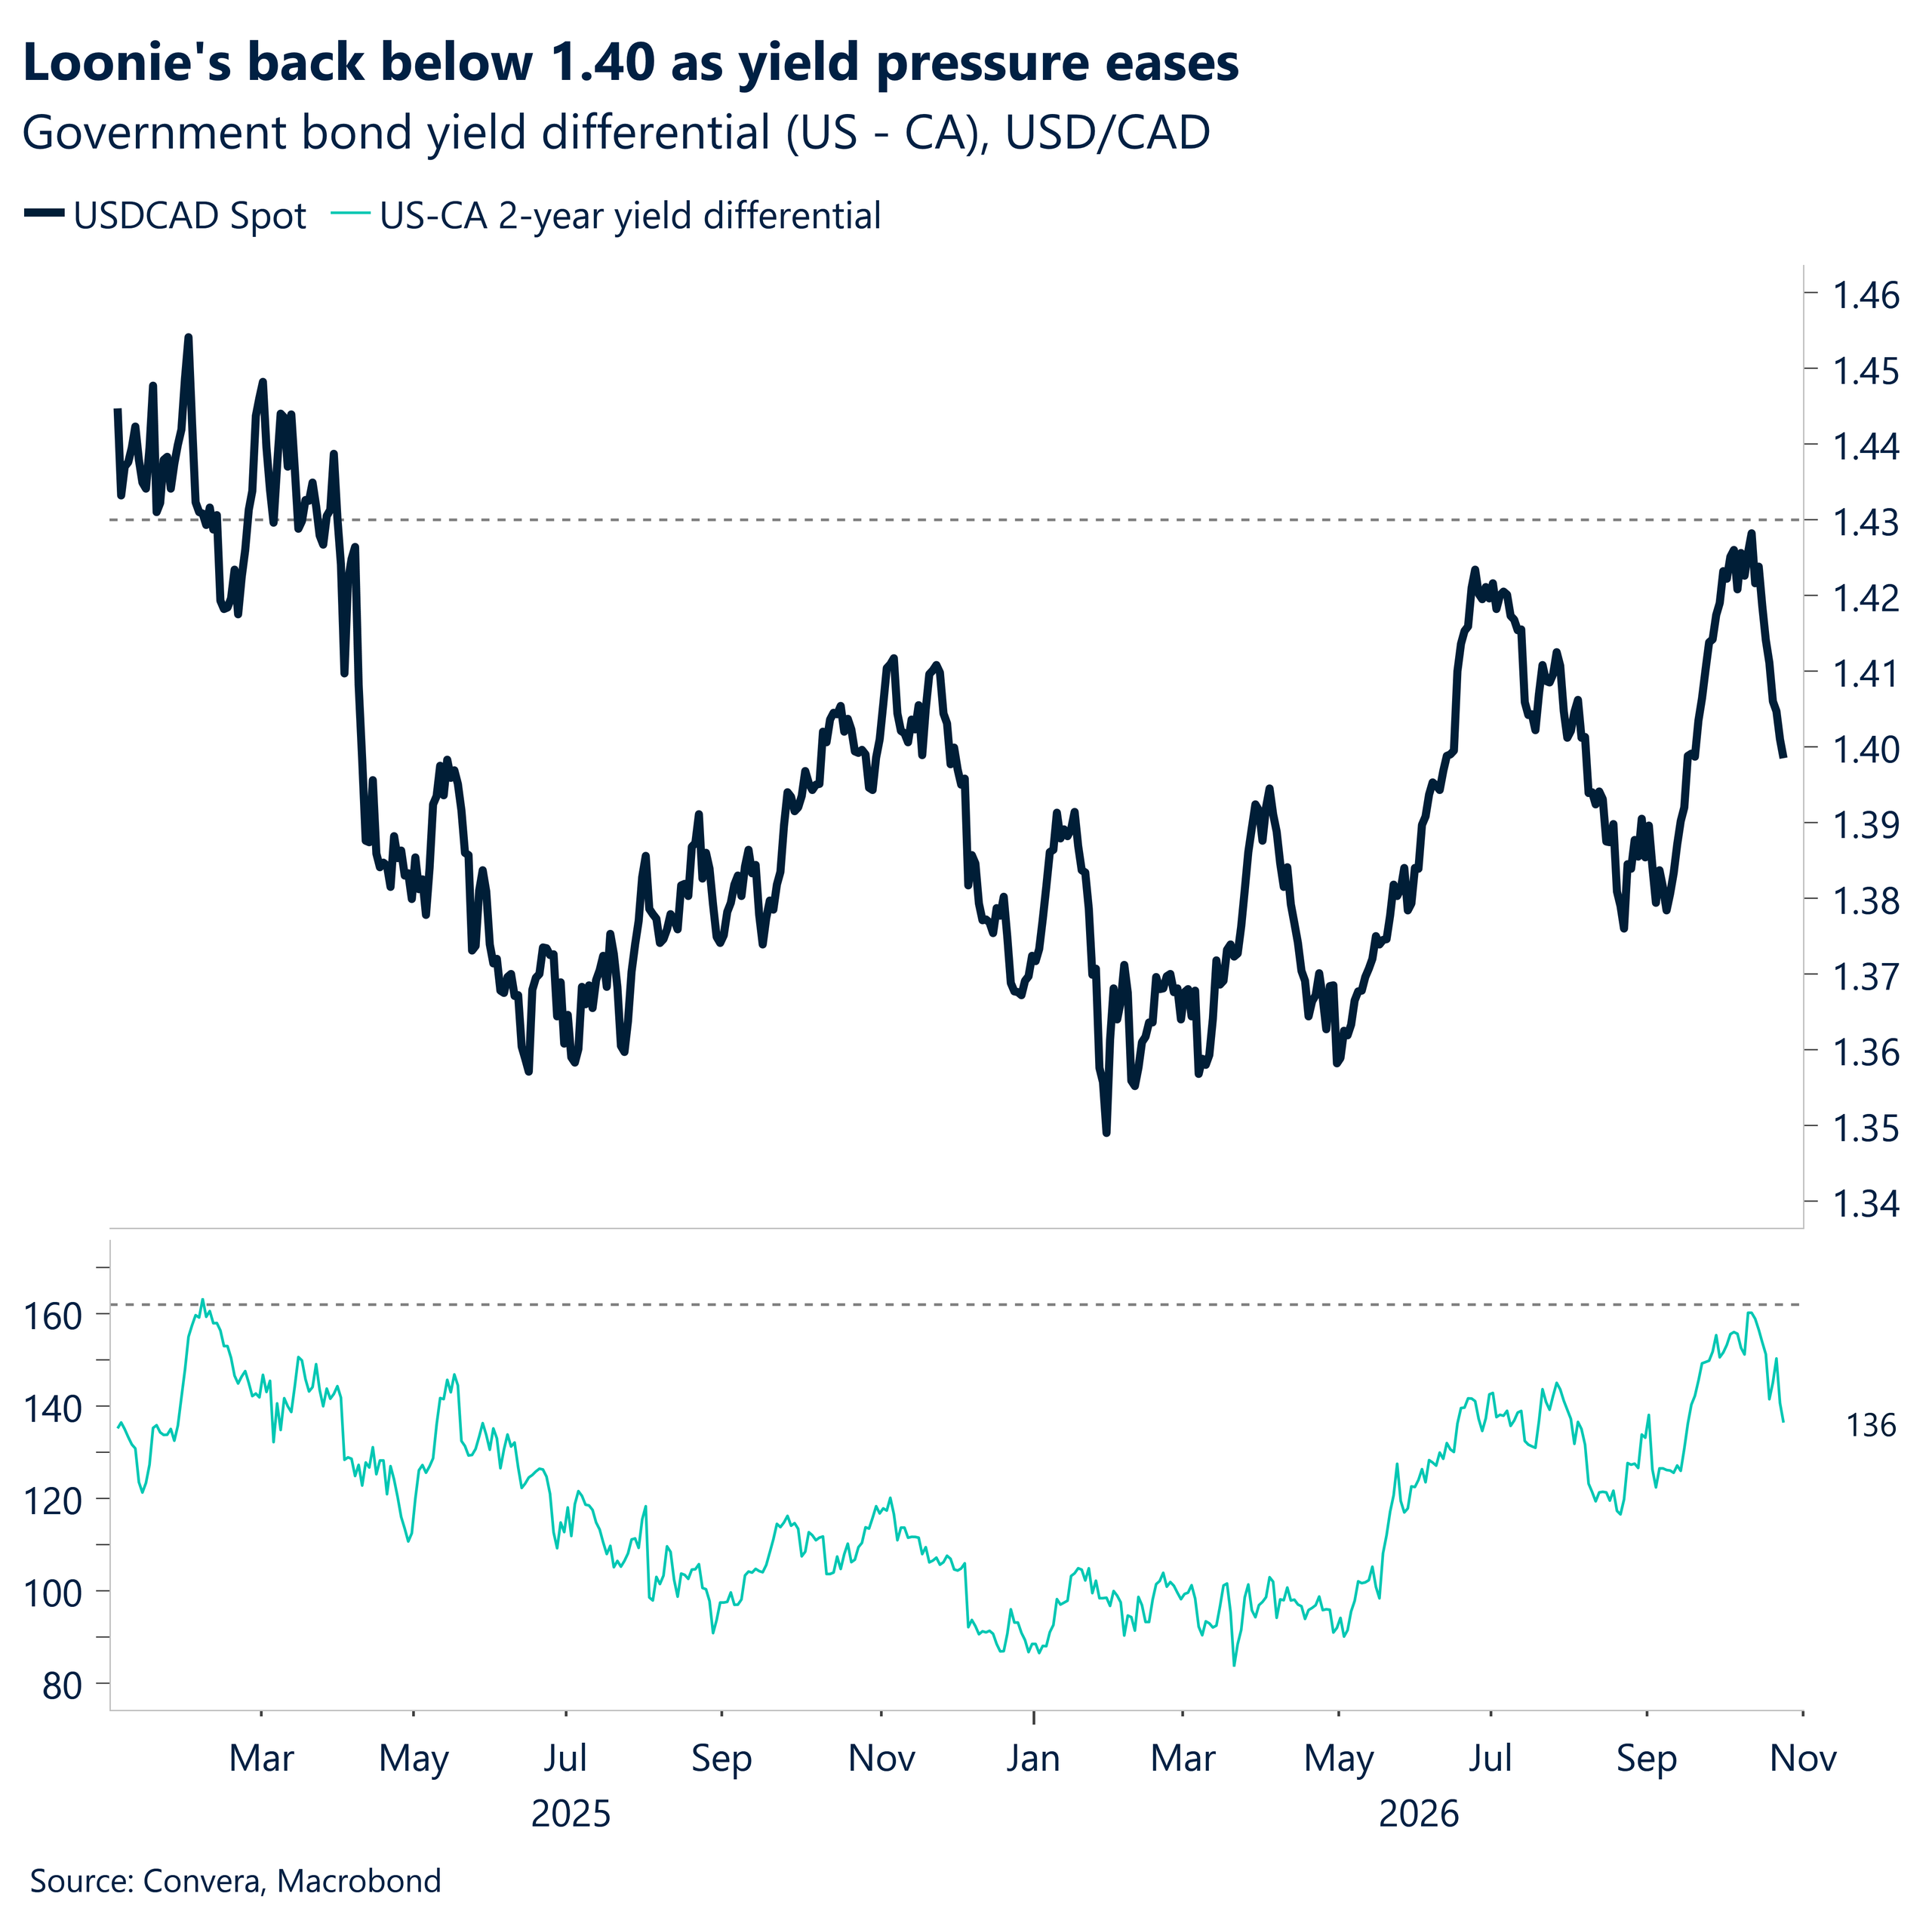
Canadian retail sales provided the domestic support the loonie needed, with headline and ex-auto spending both rising 1.2% in August. The preliminary 0.7% increase for September suggests that momentum carried into the fourth quarter, challenging the view that the Canadian consumer is already buckling under higher borrowing costs. Combined with an 80% probability of an October 28 Bank of Canada hike, the data helped push USD/CAD below 1.40.
As mentioned for Reuters, the larger driver remains the direction of relative rates. The US-Canada two-year spread is still wide at roughly 136 basis points in favour of the US, but rising Canadian yields have narrowed that gap as markets bring forward the Bank of Canada’s policy path. The loonie can continue to strengthen while rate expectations converge, even if US yields remain higher.
With a 25-basis-point hike now largely priced, the decision itself may not be enough to extend the move. USD/CAD could test 1.395 if Governor Macklem signals that another increase remains possible in December, while a hold or a hike accompanied by cautious guidance would risk a sharp reversal. Upcoming GDP data must also confirm that the strength in household spending extends to the broader economy. For now, retail resilience and narrowing yield spreads favour further CAD gains, but next week’s meeting leaves little room for the Bank of Canada to disappoint.
Trade strains deepen Peso’s carry breakdown
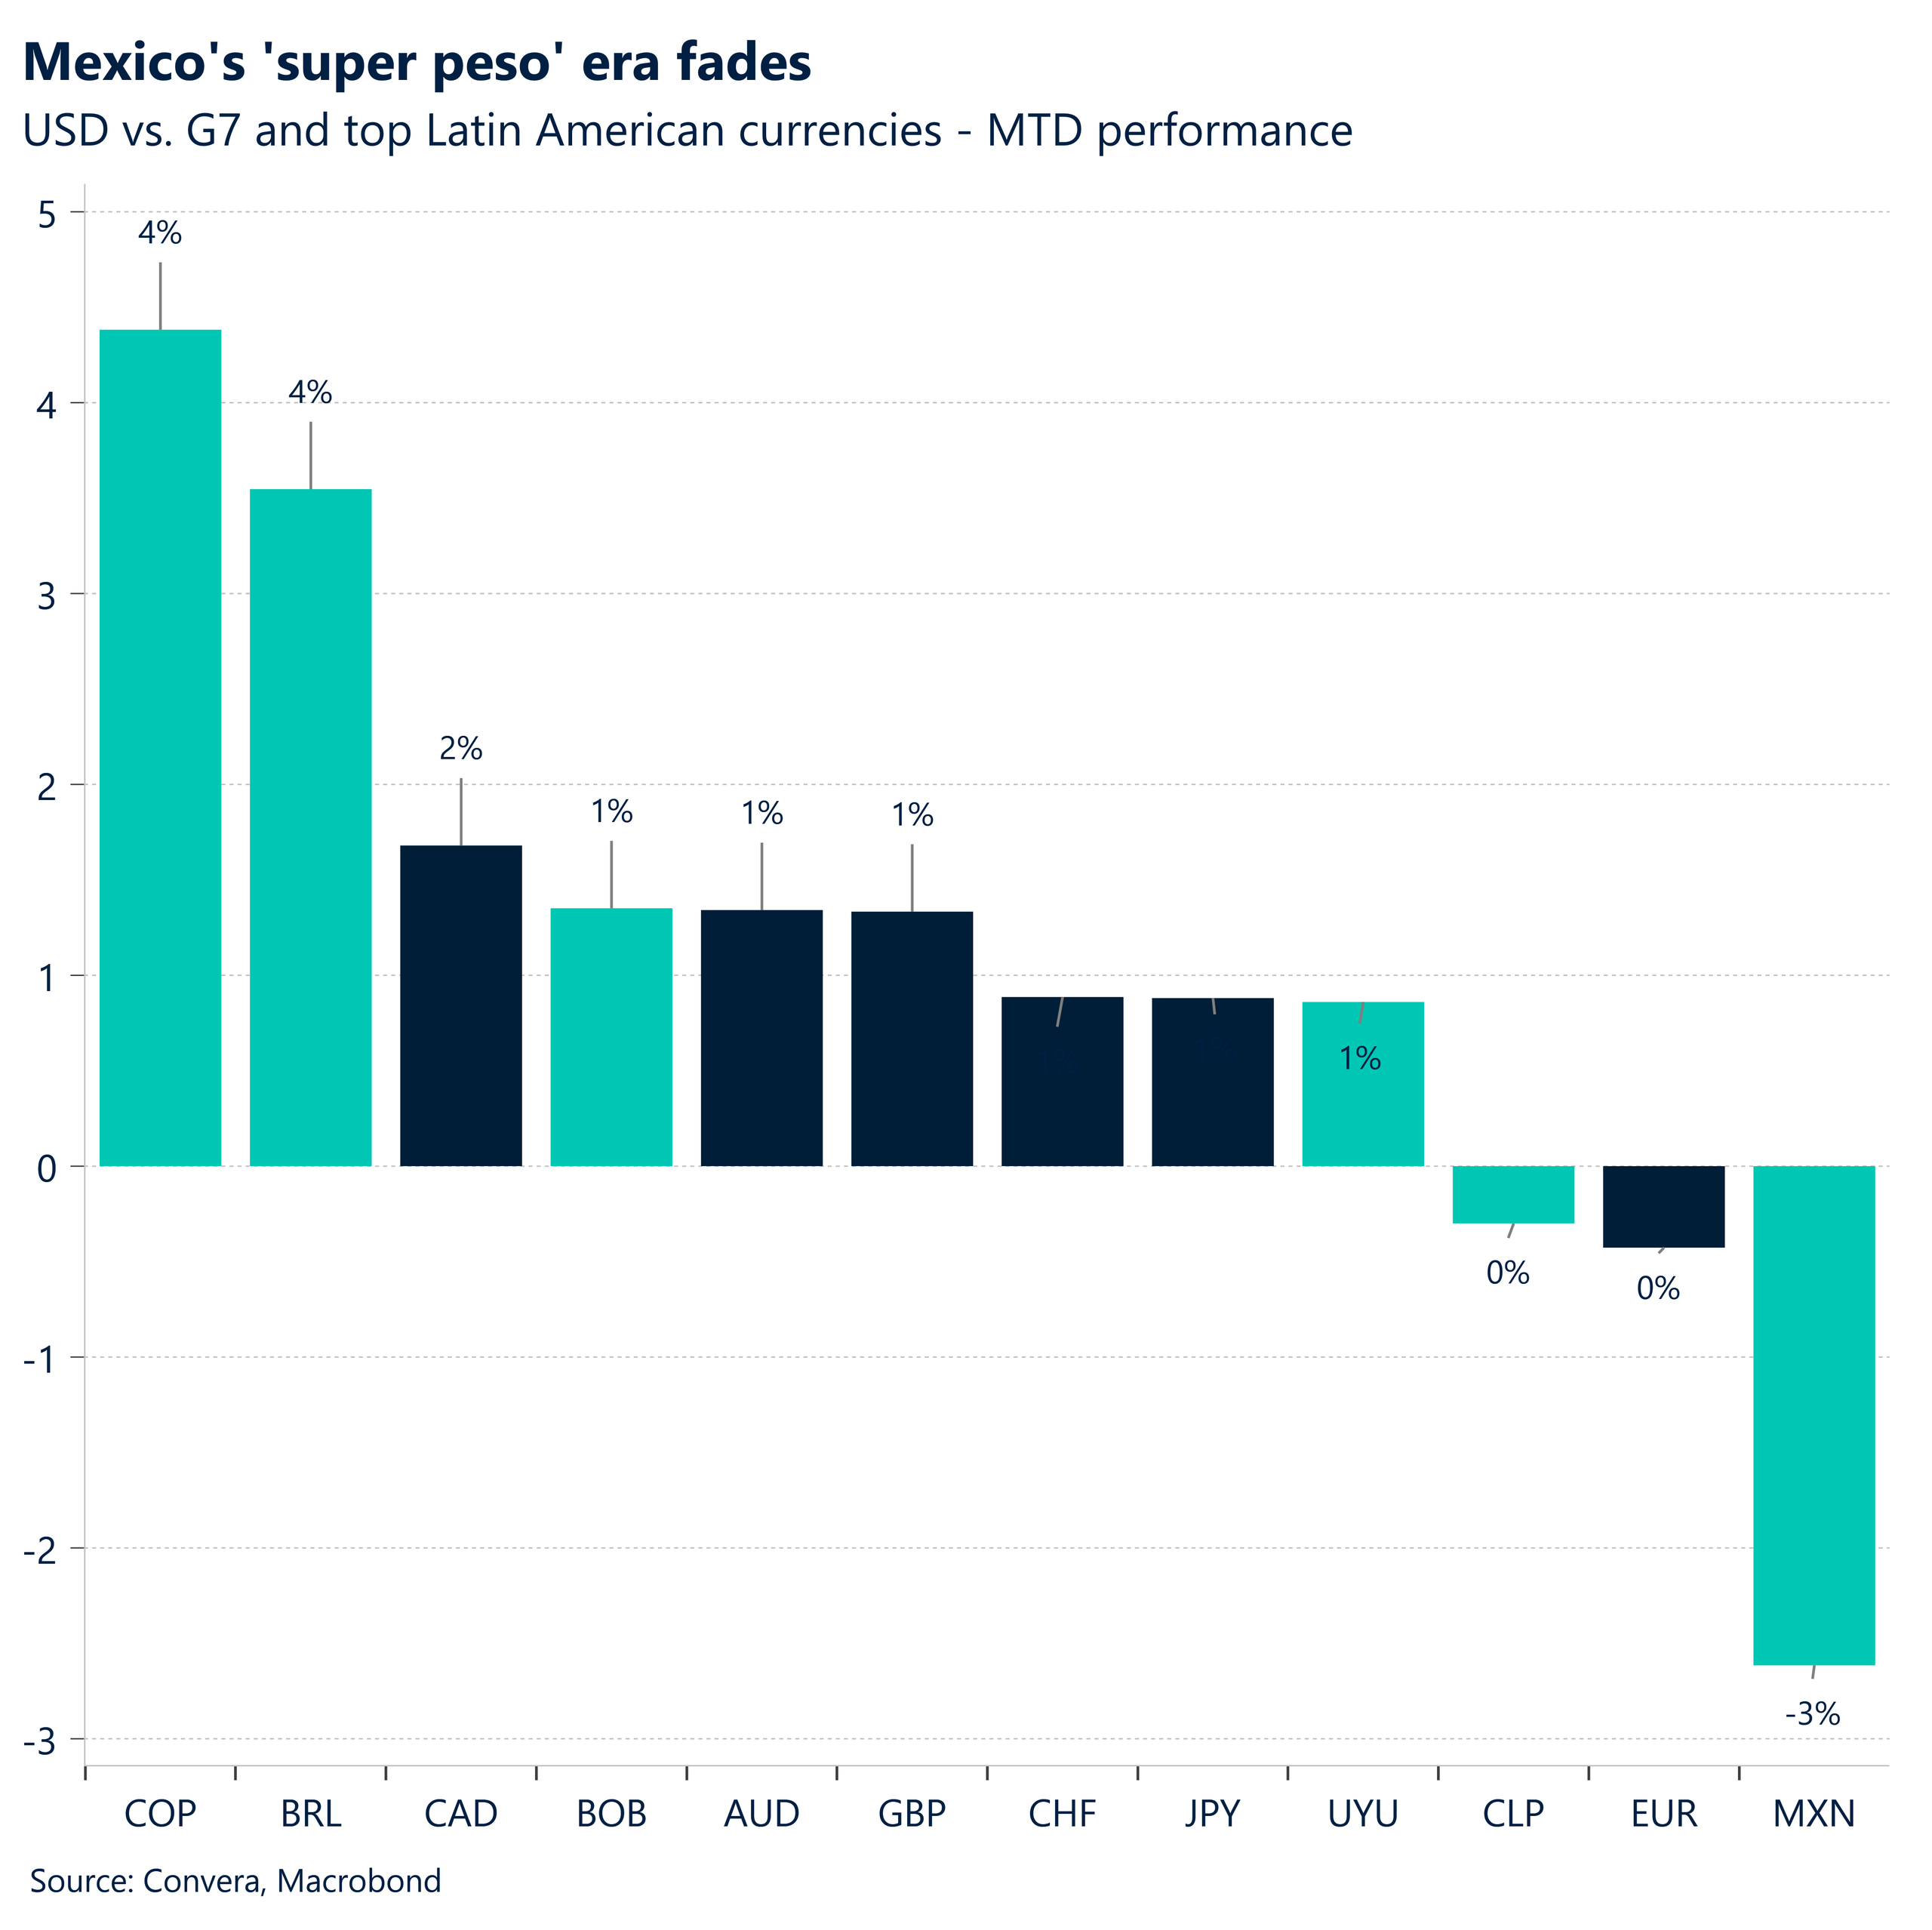
The Mexican peso’s underperformance shows that high nominal yields are no longer enough to offset its growing risks. USD/MXN has traded above 18.85, while the Mexico-US two-year yield spread has fallen below 300 basis points, eroding the cushion that previously absorbed external shocks. Record bearish positioning adds to the pressure as systematic carry strategies move from supporting the peso to accelerating the unwind.
Hotter early-October inflation complicates that move without fully reversing it. Sticky core price pressures make a November 5 Banxico cut more difficult to justify, but softer domestic activity prevents the central bank from offering a clear higher-for-longer signal. Trade friction is adding another constraint, with no breakthrough on steel and aluminum and oil near $111 raising Mexico’s imported fuel costs. Until Banxico pushes back more firmly against easing expectations or trade talks produce a concrete agreement, the peso lacks a reliable catalyst for recovery.
The break above the previous 18.69 high shifts that level from resistance to support, while the pullback toward 18.79 looks more like consolidation. Upcoming third-quarter GDP data could deepen Banxico’s dilemma if growth slows while inflation remains firm. Crowded short positioning leaves room for a sharp rebound on a hawkish policy surprise or confirmed trade progress, but without either catalyst, USD/MXN remains biased toward 19.0.
Market snapshot
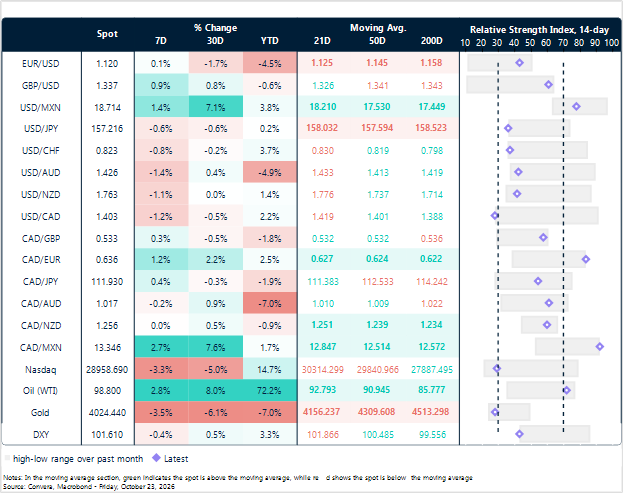
Table: Currency trends, trading ranges & technical indicators
Key global risk events
Calendar: October 19 – 23
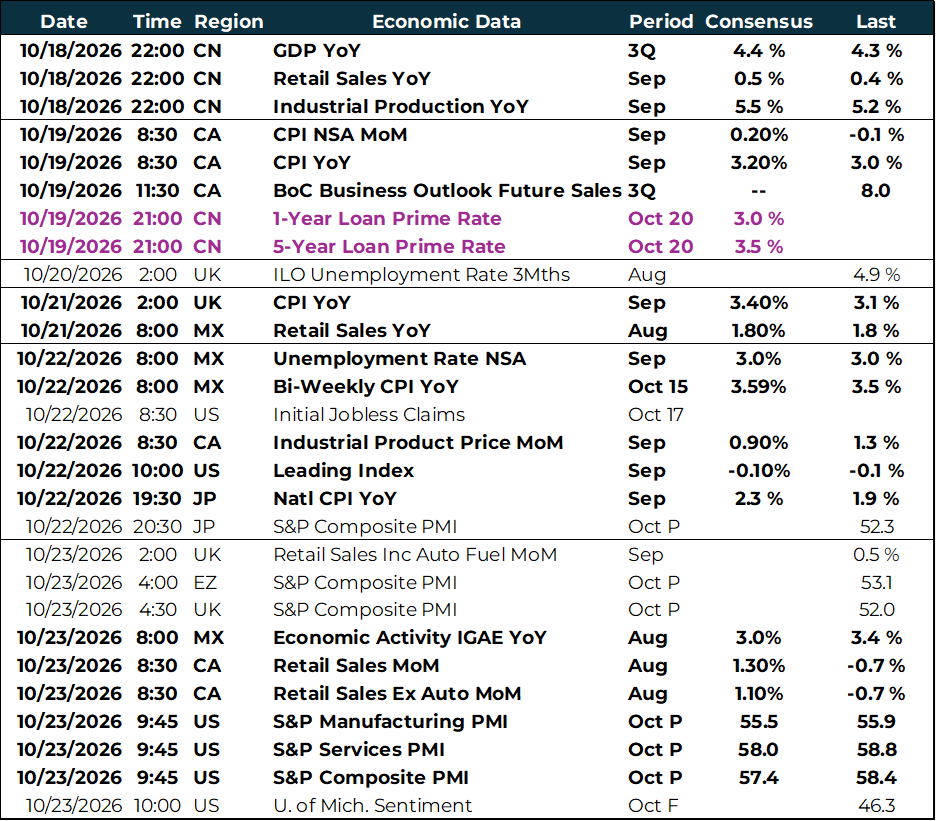
All times are in EST
Have a question? [email protected]
*The FX rates published are provided by Convera’s Market Insights team for research purposes only. The rates have a unique source and may not align to any live exchange rates quoted on other sites. They are not an indication of actual buy/sell rates, or a financial offer.